
Buying a home in Brooklyn comes with plenty of decisions, from choosing the right neighborhood to determining how much space you need. But one decision that can surprise even experienced buyers is whether to purchase a condominium or a cooperative apartment, commonly called a co-op.
Co-ops are a significant part of New York City's housing market and can offer an appealing path to homeownership. However, they come with specific financial requirements, approval processes, and ownership rules that buyers should understand before making an offer.
If you're exploring homes for sale in Brooklyn, here are seven things to consider before purchasing a co-op.
1. You're Buying Shares, Not the Apartment Itself
Unlike a condo, where you own your individual unit, purchasing a co-op means buying shares in a corporation that owns the building. Those shares give you the right to occupy a specific apartment through a proprietary lease. This structure affects everything from renovation permissions to subletting policies.
What to do: Have your real estate attorney review the building's bylaws, proprietary lease, and house rules before committing to a purchase.
2. Board Approval Is Part of the Process
Co-op buyers typically submit an application detailing their finances, employment, assets, and other relevant information. Many buildings also require an interview with the board. Even financially qualified buyers can experience delays if documents are missing or additional information is requested.
What to do: Ask about the board application process early. Prepare your financial documents in advance and work with your agent and attorney to understand the requirements and timeline.
3. Monthly Maintenance Adds Up
A co-op's monthly maintenance fee generally covers building operating expenses and property taxes. It may also include payments toward an underlying building mortgage. A lower purchase price doesn't necessarily mean lower overall housing costs. Maintenance fees can increase, and some buildings may impose special assessments for major repairs.
What to do: Calculate your total monthly expenses, including your mortgage, maintenance, insurance, and utilities. Ask about recent fee increases and anticipated building expenses.
4. Your Financial Profile Matters
Co-op boards often have financial requirements beyond those imposed by mortgage lenders. Depending on the building, buyers may need a larger down payment, substantial cash reserves after closing, or a debt-to-income ratio within a specified range. Qualifying for a mortgage doesn't automatically guarantee co-op board approval.
What to do: Establish your budget with a lender and ask about each building's financial requirements before submitting an offer.
5. Subletting Rules Can Limit Flexibility
Planning to relocate for work, move into a larger home, or rent out your apartment in the future? Check the building's subletting policies first. Some co-ops restrict how long owners can rent their apartments, require board approval, or prohibit subletting under certain circumstances.
What to do: Consider your plans for the next five to ten years. Understanding these restrictions now can help you avoid purchasing a property that no longer suits your needs later.
6. Look Beyond the Apartment
An attractive apartment doesn't tell you everything about the building's financial health. Building reserves, outstanding loans, deferred maintenance, and upcoming capital improvements can affect your future costs as a shareholder.
What to do: Ask your attorney to review available financial statements, board meeting minutes, and relevant building documents. Understanding potential expenses can help you evaluate the purchase more thoroughly.
7. Choose a Neighborhood That Fits Your Life
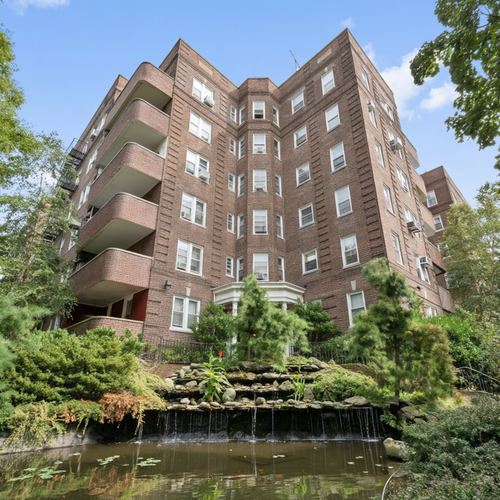
Brooklyn offers a variety of co-op options, from prewar buildings in Park Slope and Prospect Heights to residential communities in Kensington and Bay Ridge. Consider your commute, access to parks and local businesses, building policies, and long-term plans. For first-time buyers, growing households, and people moving to NYC, these everyday details matter just as much as the apartment itself.
What to do: Visit neighborhoods at different times of day and think about how each location would fit your daily routine.
Find the Right Co-op With Confidence
Buying a Brooklyn co-op requires preparation, but understanding the process can help you make a more informed decision.
The Scott Klein Team helps buyers navigate Brooklyn's real estate market with local knowledge, thoughtful guidance, and a focus on their individual goals. Whether you're purchasing your first home or moving into a space that better suits your needs, we're here to help you understand your options.
Explore our buyer representation services to learn more.
Considering a co-op in Brooklyn? Reach out to The Scott Klein Team or complete our buyer intake form to schedule a 15-minute discovery call. We'd be happy to discuss your plans and help you determine your next steps.
Check out this article next